
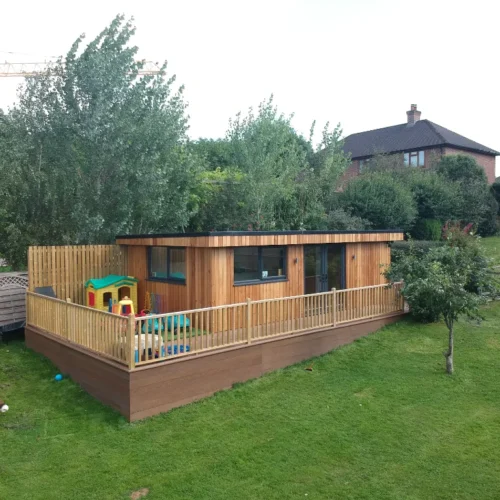
Once your garden room is built, it’s easy to assume your existing home policy simply extends to cover it. Most of the time, it can, but only if the insurer knows it’s there. Garden room insurance isn’t usually a separate product you have to go out and buy. It’s more a case of making sure your current policy has been updated to recognise the new structure, what’s inside it, and how you use it.
Get that right and you’re covered properly from day one. Get it wrong and you may find a claim doesn’t pay out when you need it to.
Does Home Insurance Cover a Garden Room?
In most cases, yes, though it depends entirely on what you tell your insurer. Garden rooms are usually treated as outbuildings rather than an extension of the main house, so cover typically falls under the outbuildings or garden structures section of a standard home policy rather than being automatic.
The important part is declaration. If your insurer doesn’t know the garden room exists, or hasn’t been told about its value, size, or how it’s used, a claim can be refused even if your policy technically includes outbuilding cover. It’s worth contacting your insurer as soon as the room is finished, rather than waiting until renewal, so the structure is recognised straight away and there’s no gap where you’re effectively uninsured.
Garden Room Buildings Insurance Explained
Garden room buildings insurance covers the structure itself against risks such as fire, storm damage, flooding, theft, and vandalism, in the same way your main house is protected. Whether your policy includes this automatically depends on the specifics of the build.
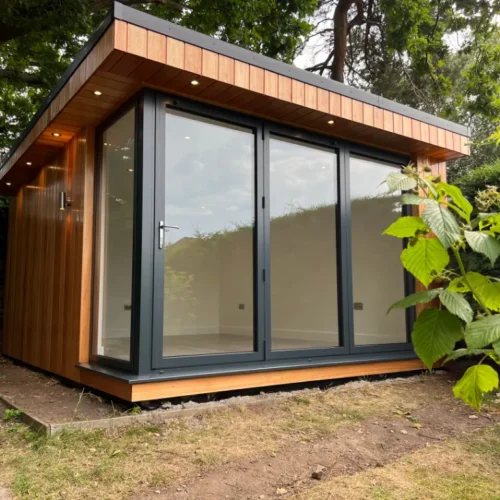
A garden room with permanent foundations and fixed electrics is generally easier to insure as a proper outbuilding, since it’s clearly a lasting structure rather than something temporary. This is one of the reasons garden room insurance is worth sorting properly rather than leaving to assumption.
Insurers will often ask about construction type, so having details of the materials, foundations, and any electrical installation ready makes the process straightforward. It’s also worth checking whether your policy’s rebuild cost needs updating, since adding a substantial new structure to your property can affect the overall figure your insurer uses to calculate cover.
What About the Contents Inside?
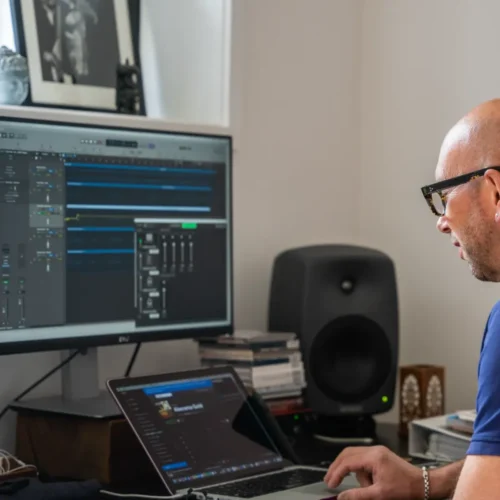
Garden room contents insurance works differently to buildings cover, and it’s the part people most often overlook. Standard home policies often extend some contents cover to outbuildings, but usually with a lower limit than applies inside the main house.
If your garden room houses a home office setup, a gym, or anything of real value, it’s worth checking that limit carefully. Items commonly worth listing separately include:
- Laptops and computer equipment
- Specialist tools or workshop equipment
- Musical instruments
- Gaming or entertainment systems
- Furniture and furnishings above standard value
If the total value of what’s inside exceeds your outbuilding contents limit, you can usually ask your insurer to increase it or list high-value items individually. It only takes a phone call, and it’s a simple way to keep your garden room insurance matched to what’s inside.
Insuring a Garden Office or Other Business Use
Insuring a garden office gets more complicated the moment it’s used for anything beyond personal, domestic purposes. Working from home occasionally is usually fine under a standard policy, but running a business from the space, seeing clients, or storing stock changes things considerably.
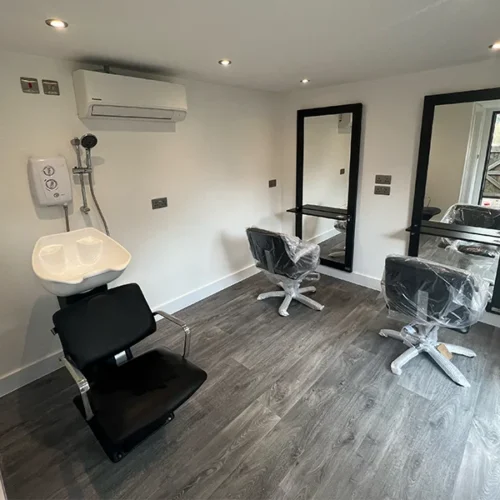
If you’re using your garden room as a therapy room, a salon, a rental unit, or any space where clients or customers visit, most standard home insurance won’t cover you for that use. Standard garden room insurance is built around personal, domestic use, so you’d typically need a business insurance policy or an endorsement added to your existing cover.
It’s worth being upfront with your insurer about how the space is used, even if it feels like a minor detail, since an undeclared business use is one of the more common reasons a claim gets rejected.
Do You Need Separate Insurance for a Garden Room?
Whether you need separate insurance for a garden room comes down to a handful of factors, such as the size of the structure, its value, how it’s used, and whether your current policy’s terms stretch to cover it.
For a straightforward garden room used for personal purposes, most homeowners find their existing home insurance is sufficient once the policy has been updated to include the new structure. Where things tend to need a separate policy or additional cover are larger builds, rooms used commercially, or situations where the contents inside significantly exceed standard outbuilding limits. If you’re not sure which category you fall into, it’s worth having a conversation with your insurer directly rather than assuming either way.
Getting Garden Room Insurance Right in the UK
Garden room insurance in the UK isn’t complicated once you know what to check, but it does require a bit of legwork on your part rather than assuming everything’s covered by default. A few checks make sure your policy does what you expect it to.
Before you consider the job done, it’s worth working through the following:
- Confirm the garden room is classed as an outbuilding under your policy
- Tell your insurer as soon as the structure is complete
- Check the buildings cover limit applies to the new structure
- Review the contents limit for items kept inside
- Declare any business or income-generating use
- Update your rebuild cost figure if needed
Most of this takes a single phone call, and it means you’re properly protected rather than hoping for the best.
Let’s Make Sure Your Garden Room Is Properly Covered
At Garden Room Solutions, we design and build bespoke garden rooms across Dorset and the surrounding areas, and we know that getting your new space properly insured is as important as getting it properly built. While we’re not insurance specialists, we’re always happy to talk through the build spec, foundations, cladding, windows and doors, and electrics of your garden room so you’ve got everything you need when you speak to your insurer.
If you’re planning a build or want to talk through your options, give us a call on 01202 081198 or get in touch through our contact form. We’ll help you get it right from the ground up.